What You'll Learn
Before taking action, review the foundational milestones covered in this blueprint.
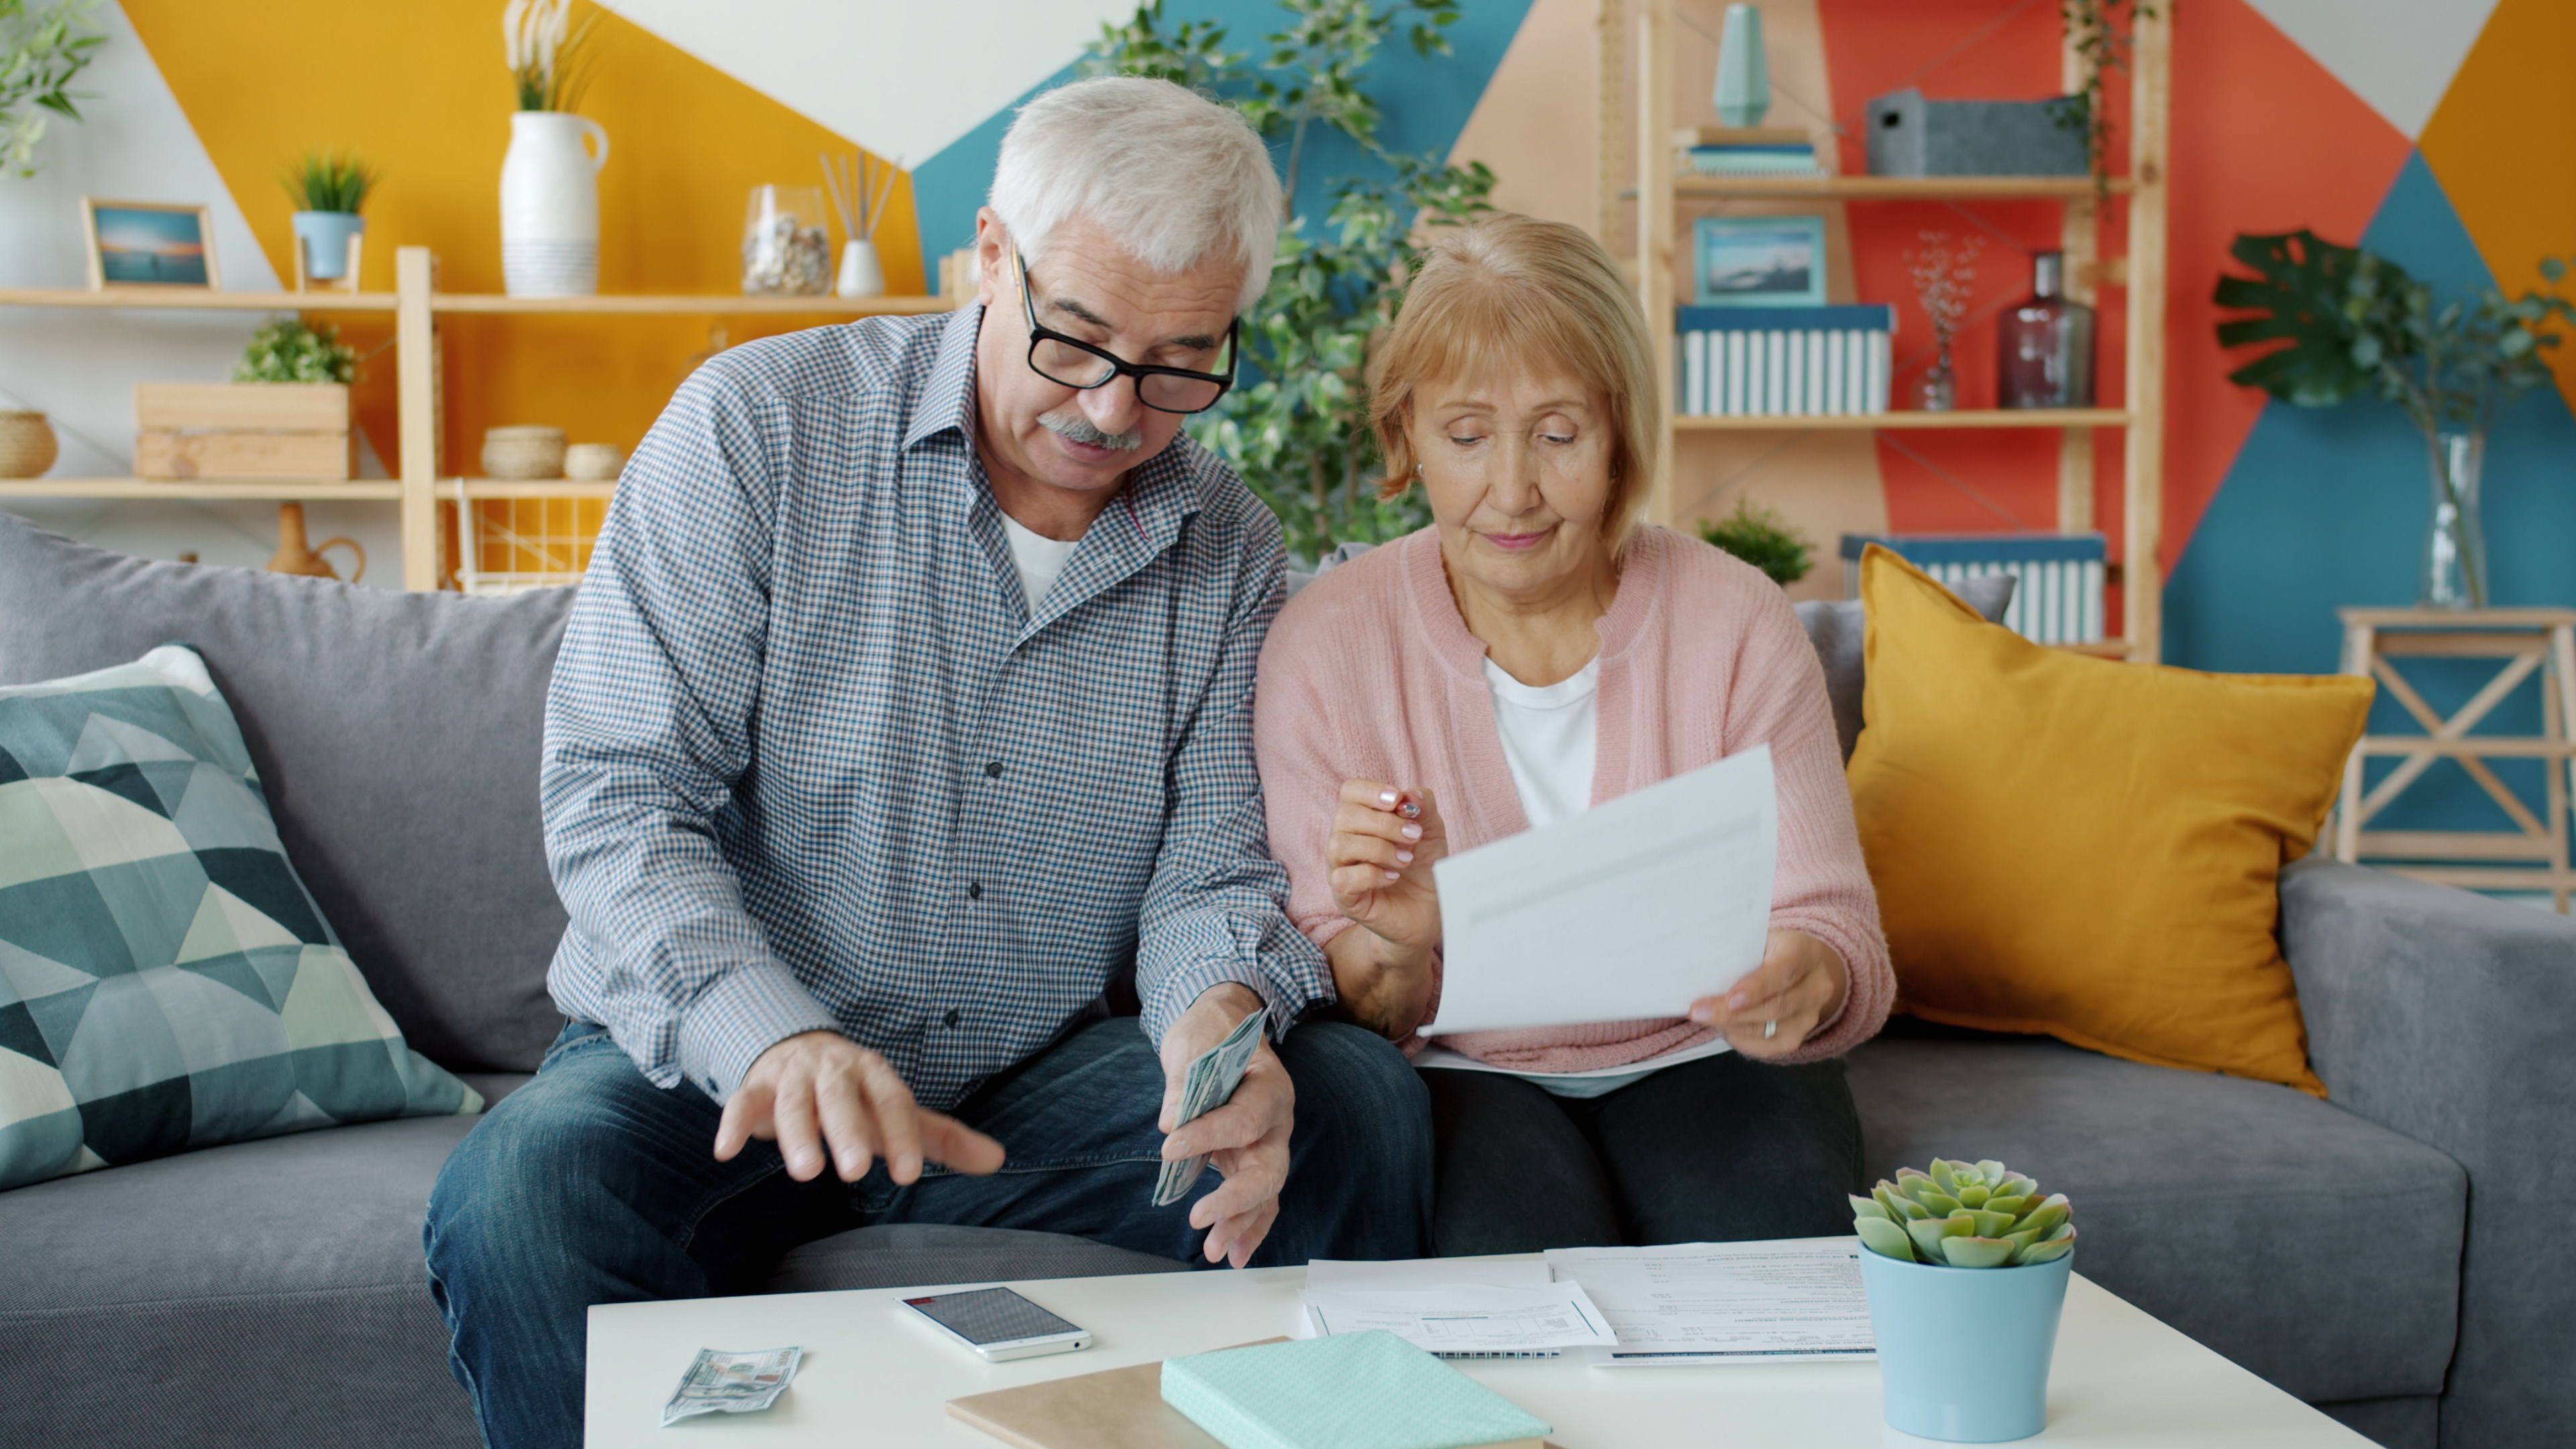
Cash advance loans can provide fast access to money when an unexpected bill cannot wait. A car repair, medical expense, overdue utility bill, or seasonal purchase can put real pressure on your budget. Before you apply, we recommend looking at the repayment date, total amount owed, and other funding choices, not just how quickly money may arrive.
Fall can bring heating bills, back-to-school costs, vehicle maintenance, and early holiday shopping. Planning for those expenses before the holiday season may help you avoid borrowing more than you can realistically repay. We created this guide to help you understand short-term borrowing, compare possible options, and choose a payment plan that works with your budget.
How Cash Advance Loans Work Before You Apply
Cash advance loans are a broad term for short-term financing that may provide smaller amounts of money quickly. Depending on the lender and your state, you may see payday loans, installment loans, credit card cash advances, or other small-dollar loan options. These products can look similar at first, but their payment schedules, fees, and approval requirements may be very different.
When you apply online, we may ask you to provide details such as your identity information, income, bank account information, and contact details. As an online marketplace, we connect applicants with participating NMLS-licensed lenders that may present potential loan offers. Submitting information does not guarantee approval, a loan offer, a certain amount, or a specific rate.
Repayment depends on the product you select. Before accepting an offer, we recommend reviewing:
Before Accepting Any Loan Offer, Review:
A loan agreement should clearly explain what you owe and when you owe it. If any part of the agreement is unclear, ask the lender to explain it before you agree.
Compare Fast Funding Options Carefully
Payday-style loans may offer quick funding for a short-term gap, but they can come with high fees and a short repayment window. Paying the full balance back in one lump sum can be hard if your next paycheck is already set aside for rent, food, transportation, or utilities.
Installment personal loans may give you more time to repay, with fixed payments that can be easier to plan around. Still, terms, amounts, rates, and eligibility rules vary by lender and applicant. Borrowers with lower credit scores may have fewer choices or receive offers with higher borrowing costs, which makes reading disclosures especially important.
Other options may be worth considering based on your situation:
- A small-dollar loan through a credit union
- A payment arrangement with a medical provider or utility company
- An employer paycheck advance program, if available
- Savings or support from someone you trust
- A credit card cash advance, keeping its fees and immediate interest in mind
A credit card cash advance is not automatically a lower-cost choice. It may include a separate cash advance fee, and interest may begin adding up right away. Speed matters when an expense is urgent, but it should not be the only factor.
Calculate the Full Cost Before You Borrow
The stated loan amount does not always tell the full story. Depending on the lender, state, and loan type, your disclosures may include an annual percentage rate, finance charge, origination fee, late fee, returned-payment fee, or other permitted charges. The annual percentage rate can help you compare loans with different terms and fee structures.
Before accepting any offer, we suggest writing down a few simple details:
- The exact amount you need for the expense
- The amount that will actually be deposited into your account
- Each scheduled payment and its due date
- The number of payments and the full amount you will repay
A fee taken out before funds are deposited can mean you receive less than the stated loan amount while still owing the principal plus applicable charges. That is why reviewing the amount deposited is just as important as reviewing the amount approved.
Watch the Repayment Window
A loan with a short repayment period may strain your budget even if the borrowed amount seems manageable. We recommend looking at your full budget through the final payment date, not only at what you can afford today. Loan availability, fees, and terms can vary by lender, state, and your qualifications.
Avoid Debt Traps and Protect Your Information
Short-term financing is generally best used for a specific, temporary need, not an ongoing budget gap. If you find yourself needing new financing each month for groceries, bills, or earlier loan payments, we recommend stepping back and considering a longer-term budgeting or credit counseling solution.
Extensions, rollovers, and repeat borrowing can make a balance harder to manage. Replacing one loan with another or extending a due date may add fees and increase the amount you owe. Before agreeing to an extension, make sure you understand its terms and whether it changes your repayment amount or schedule.
We also encourage you to watch for signs of a possible loan scam. Be cautious when a company:
- Guarantees approval before reviewing your information
- Requests an upfront payment before funding a loan
- Pushes you to act immediately without time to review terms
- Asks for payment through gift cards, cryptocurrency, or wire transfers
- Requests your online banking login credentials
For fall expenses such as heating costs, repairs, travel, or holiday purchases, check whether the provider has a payment plan, hardship program, or deferred billing option. Those arrangements may reduce the need for high-cost borrowing.
Build a Repayment Plan Before You Borrow
A clear repayment plan can help fast funding remain a short-term solution instead of becoming a longer-term problem.
Start by identifying the exact amount you need, then confirm that every scheduled payment fits within your upcoming pay periods. Read the lender's disclosures, repayment schedule, fees, and state-specific availability before accepting a loan. Borrow only what you need, and choose an option that supports your overall financial stability.
Find a Cash Advance Option That Fits
At PrimeLendings, we help you review cash advance loans with clear information about available options and next steps. Our team is here to help you understand the process and answer general questions before you apply. Start your application to see what options may be available, or contact us for support. You can also read our guide on payday loans versus personal loans for additional context on how short-term products compare.
Topics
CFP® · Senior Financial Analyst
Sarah Chen is a Certified Financial Planner (CFP®) with 15+ years in consumer credit, loan underwriting, and personal finance coaching. She has worked directly with hundreds of bad-credit borrowers to identify the most appropriate lending pathways.
Editorial Standards: This blueprint has been reviewed by a Certified Financial Planner (CFP®) for accuracy and regulatory compliance. PrimeLendings maintains complete editorial independence — lender commercial relationships never influence our educational assessments.