What You'll Learn
Before taking action, review the foundational milestones covered in this blueprint.
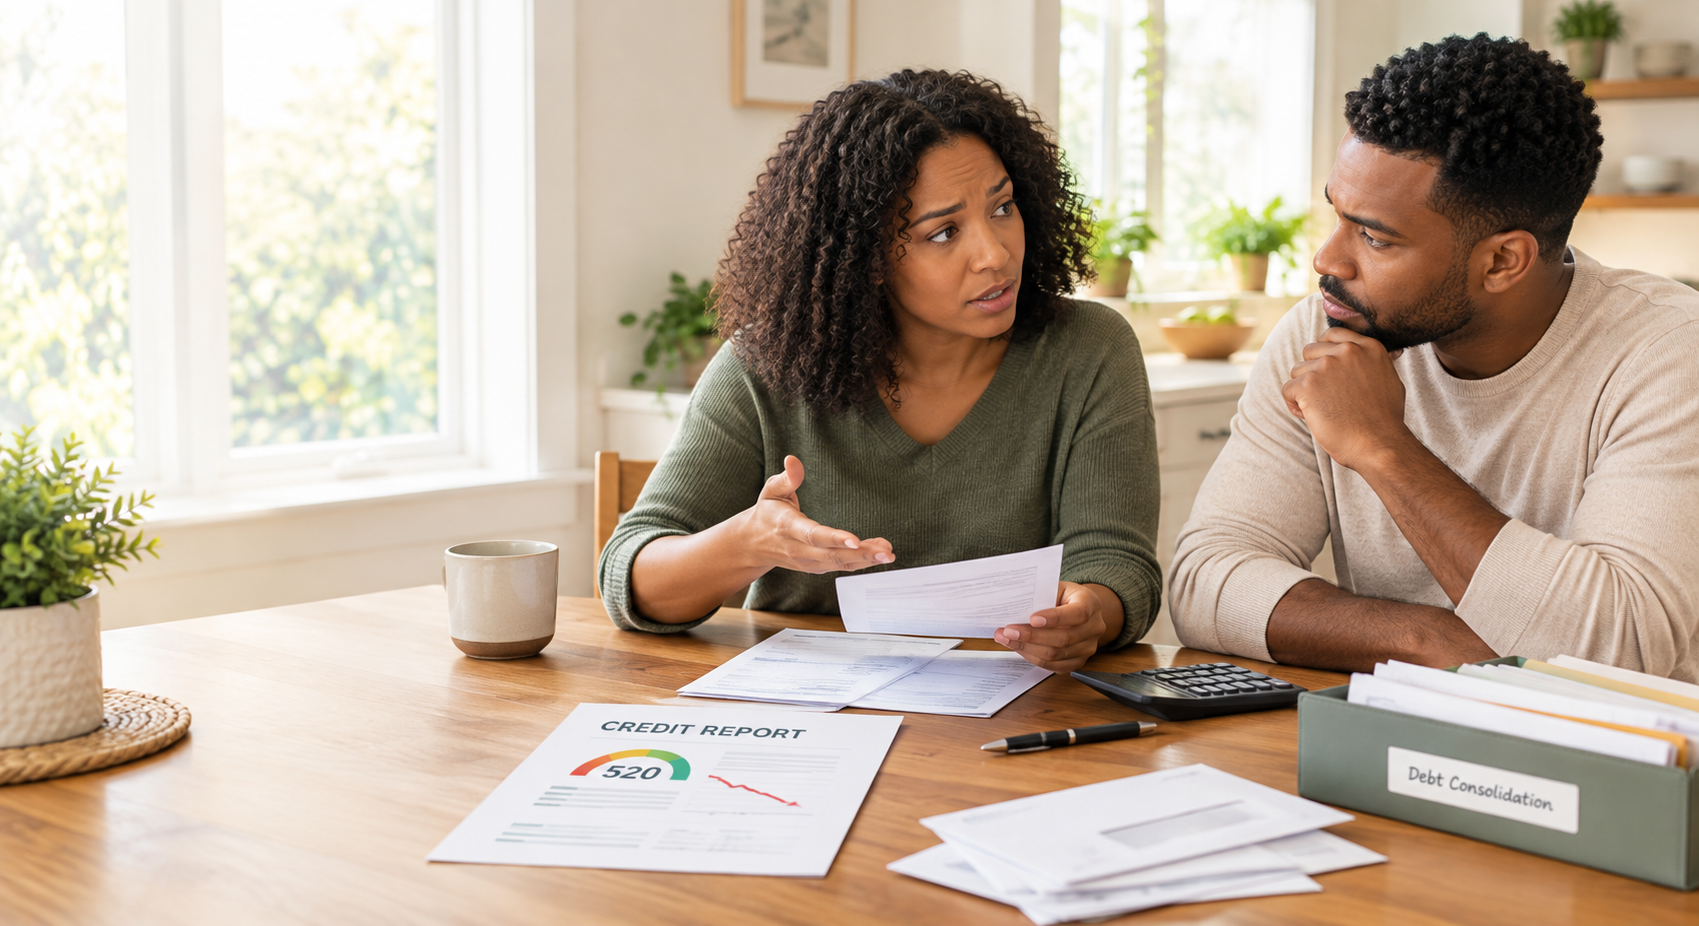
Bad credit debt consolidation may help you turn several stressful payments into one scheduled payment. We want you to start with clear expectations: a new loan can simplify repayment and may improve your payment situation, but whether it helps depends on your budget, financial profile, and the lender's terms.
October is a smart time to review debt before holiday shopping, travel, heating bills, and year-end expenses create more pressure. Before you apply, we recommend listing your balances, due dates, interest charges, and required monthly payments so you know exactly what you are trying to solve.
Why Guaranteed Approval Claims Need Careful Review
"Guaranteed approval" sounds reassuring when bills are piling up, but no legitimate lender can promise approval before reviewing your application. Lenders generally need to verify identity, income, ability to repay, residency, bank account information, and any requirements that apply in your state. Credit history may be part of the review, but it is not always the only factor.
We encourage you to pause when an offer seems too easy or avoids basic questions about your finances. Clear loan disclosures matter because they show what you may be agreeing to before you accept.
Watch for warning signs such as:
Warning Signs to Watch For:
At PrimeLendings, you can submit a loan request online. We do not promise that everyone will qualify, because the lender decides approval, loan amount, rate, and repayment terms. Honest expectations are safer than a promise that cannot be kept.
How Bad Credit Debt Consolidation May Work
Debt consolidation means using one new loan to pay off more than one existing debt. Instead of tracking several due dates, you make one payment to the new lender on a set schedule. Depending on the lender and the debts involved, this may be used for credit card balances, medical bills, installment loans, overdue accounts, and certain payday loans.
For many people, the appeal is simple: fewer moving pieces. A consolidation loan may provide a clearer payoff date and make a monthly budget easier to follow. In some cases, it may also offer a lower payment or more favorable borrowing terms than the debts you currently carry.
A lower payment does not always mean lower total repayment. Stretching debt over a longer period can make the payment feel more manageable while increasing the amount paid over the life of the loan. That is why we encourage you to compare the full offer, not just the number due each month.
Our online request process can help you explore possible options without visiting lender sites one by one. A soft-pull rate check may let you review potential offers without an initial hard credit inquiry. If you choose to move forward with a formal application, the lender may later complete a hard credit check. You can also compare lender options through our marketplace before you decide.
Compare More Than the Monthly Payment
A debt consolidation offer should fit your full financial picture, not simply provide short-term breathing room. Before accepting anything, compare the annual percentage rate, repayment length, applicable fees, late-payment rules, prepayment policy, and total amount you would repay. Review our loan rates and fees guide to understand what to look for.
Start with a simple snapshot of your current debts. Gather the details in one place so you can compare your existing payments with any new offer.
Your debt snapshot can include:
Build Your Debt Snapshot Before You Compare:
This review can show whether a consolidation loan creates real improvement or simply delays the problem. We also recommend making a plan for the accounts you pay off. If credit cards are cleared but then charged back up, you could end up with both new card debt and a consolidation payment.
Before holiday spending begins, set a realistic limit for gifts, travel, food, and seasonal events. A consolidation loan works best when it is focused on qualifying existing debt, not treated as extra money to spend.
Build a Stronger Application and Review Real Options
Even with a low credit score, preparation can help you present a clearer application. Check that your name, address, employment details, and bank information are correct. Reviewing your credit report for possible errors can also be worthwhile, as can gathering proof of income and a clear list of your regular expenses.
Lenders may look at whether you have dependable income left after housing, utilities, transportation, food, and other required obligations. For that reason, we suggest requesting only the amount needed to handle the debts you plan to consolidate. Reviewing our loan eligibility guide can help you understand what lenders may consider. Choosing a payment that fits your real budget is more helpful than seeking the largest amount available.
Avoid Sending Too Many Applications at Once
Rather than sending many full loan applications at once, you may first review potential matches through our marketplace. This can help you focus on offers that may be more realistic for your information while avoiding unnecessary applications. Requirements can vary by lender and state, and not every applicant will receive an offer.
When an offer appears, read every part of it before making a decision. Confirm that the loan amount is enough to cover the debts you intend to pay and understand whether you will pay creditors yourself or whether another process applies. Keep copies of the agreement and repayment schedule so you know what is due and when.
Clear Expectations Support Better Debt Decisions
Bad credit debt consolidation can be useful for some borrowers, but guaranteed approval is not a responsible expectation. We believe the better approach is to compare transparent offers, understand the lender's disclosures, and choose a payment that supports a steady repayment plan.
Before applying, review your debts, monthly budget, and upcoming seasonal expenses. Borrow only what you need, avoid adding new balances while repaying the loan, and make sure the full repayment terms work for your household before you accept.
Find a Consolidation Option That Fits
At PrimeLendings, we can help you understand bad credit debt consolidation options and what may be available based on your financial profile. Contact us to discuss your situation with a member of our team, or start your application to see what offers may be available. You can also read our guide on how income-based loans work with no credit check for more context on what lenders may review when credit history is a concern.
Topics
CFP® · Senior Financial Analyst
Sarah Chen is a Certified Financial Planner (CFP®) with 15+ years in consumer credit, loan underwriting, and personal finance coaching. She has worked directly with hundreds of bad-credit borrowers to identify the most appropriate lending pathways.
Editorial Standards: This blueprint has been reviewed by a Certified Financial Planner (CFP®) for accuracy and regulatory compliance. PrimeLendings maintains complete editorial independence — lender commercial relationships never influence our educational assessments.